
A single accident on your roof could cost you more than the entire value of your home if your contractor lacks the right coverage. When you hire an insured roofing company in Michigan, you're not just paying for shingles; you're buying a legal shield for your personal assets. Most homeowners in the Detroit area understand that a new roof is a significant investment, and it's natural to feel anxious about the potential for hidden costs or legal complications. You want a job done right the first time without the lingering fear of being held liable for a worker's injury or a sudden leak with no recourse.
This article will show you why insurance coverage is the most critical factor when choosing a local roofer and how it protects your home from liability. We'll clarify the common confusion between being licensed and being insured while showing you exactly how to verify a contractor's standing with LARA. You'll learn how professional insurance coverage serves as your primary shield against subpar workmanship and how it streamlines the process of filing a successful storm damage claim. By the end, you'll have the confidence to choose a partner who values your property's safety as much as you do.
Key Takeaways
- Understand the vital distinction between a state license and active insurance policies to avoid common hiring pitfalls.
- Learn why General Liability and Workers' Compensation are your only defense against property damage and personal injury lawsuits.
- Master the process of verifying a contractor's credentials through the Michigan LARA database and reading a Certificate of Insurance like an expert.
- Discover why partnering with a fully insured roofing company in Michigan is the most effective way to navigate complex storm damage restoration and insurance claims.
- Secure your home's long-term value by choosing an owner-operated local contractor with over 25 years of hands-on experience in the Detroit area.
What Does an Insured Roofing Company in Michigan Actually Mean?
In Michigan, the term "insured" is often used as a marketing buzzword, but for a professional insured roofing company Michigan residents can trust, it represents a specific set of legal and financial safeguards. True insurance coverage means the contractor carries active policies that protect the homeowner from the inherent risks of construction. This includes General Liability and Workers' Compensation. From a seasoned master craftsman's perspective, these documents are as essential as a hammer or a nail gun. If a contractor isn't meticulous with their paperwork, they likely aren't meticulous with your flashing or shingle alignment either.
Michigan's climate adds another layer of urgency. Our intense freeze-thaw cycles and high wind speeds mean roofing projects are physically demanding and high-risk. When a crew is working on a steep pitch during a humid Detroit summer or a brisk autumn morning, the margin for error is slim. Without proper coverage, any property damage or job-site injury becomes the homeowner's legal and financial burden. Professional standards start with clear, verifiable documentation that proves the business is stable and prepared for the unexpected.
The Difference Between Licensed and Insured
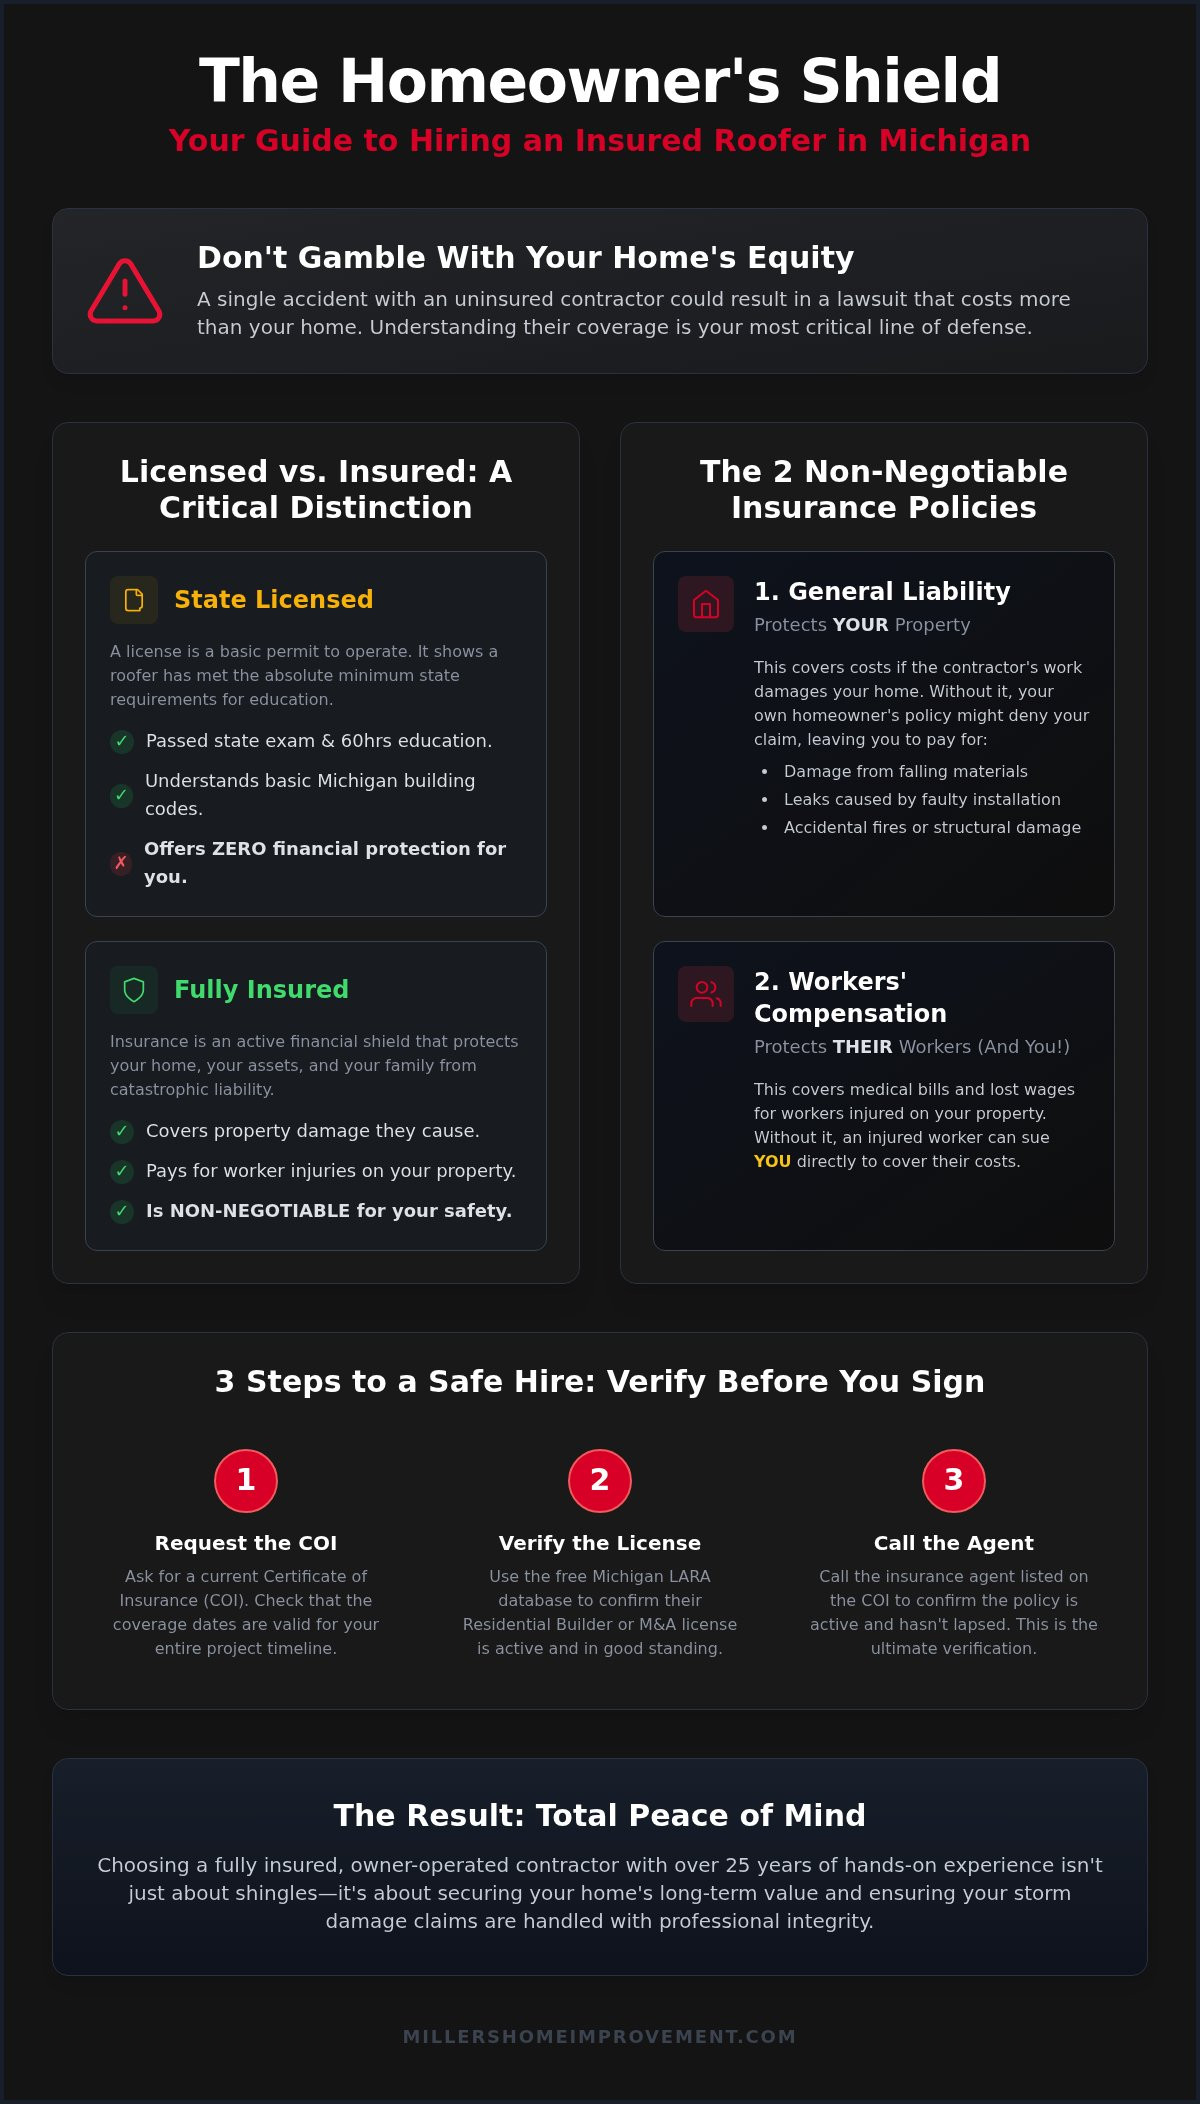
Understanding the distinction between these two terms is vital for your financial safety. In Michigan, the Department of Licensing and Regulatory Affairs (LARA) requires a Residential Builder or a Maintenance & Alteration Contractor license for any roofing work valued at $600 or more. This license proves the contractor has completed 60 hours of education and passed a state exam. It's essentially a permit to operate, ensuring the contractor understands the Michigan Residential Code and basic construction safety.
However, a license does not provide financial protection. It merely shows the state that the builder met the minimum requirements to hold a credential. If a worker falls from your eaves or a heavy bundle of shingles crashes through a skylight, the license won't pay the medical bills or repair costs. Only active insurance policies can shield your personal assets from the lawsuits that often follow such accidents. A license is the floor, but insurance is the ceiling that keeps you dry when things go wrong.
Why Insurance is a Non-Negotiable Standard
Hiring an insured roofing company Michigan homeowners rely on ensures that your home equity remains protected. While "cheap" uninsured labor might seem like a bargain, the hidden costs are catastrophic. If an uninsured contractor causes a fire or a major leak during the project, your standard homeowner's insurance policy might deny the claim because you hired an unverified entity. This leaves you paying out of pocket for repairs that should have been covered.
Professional contractors often carry specialized coverage like Builder's risk insurance to protect materials and the structure during the installation phase. At Miller's Home Improvement, we maintain active, high-limit coverage for every project we undertake. This commitment to transparency and safety is a hallmark of our 25 years of owner experience. We believe that protecting your property starts long before the first shingle is removed, ensuring our crew and your assets are fully protected under a blanket of professional accountability.
The Two Types of Insurance Every Michigan Roofer Must Have
When you look for an insured roofing company Michigan homeowners can trust, you're actually looking for two distinct types of protection. One policy covers your physical property, while the other covers the people doing the work. Relying on a contractor who only has one of these is like building a roof with shingles but no underlayment; it might look fine at first, but it won't hold up under pressure. Professional contractors maintain both to ensure that a home improvement project remains an asset rather than a liability.
Michigan law is particularly strict about how these coverages apply to employees versus subcontractors. Many companies try to lower their bids by hiring "independent" workers who lack their own policies. This creates a massive gap in protection. At Miller's Home Improvement, Eric Miller ensures every crew member is covered under the company umbrella. This approach provides a seamless layer of security for the homeowner, backed by over 25 years of owner experience in the Detroit roofing industry.
General Liability: Protection for Your Assets
Imagine a sudden Detroit rainstorm rolls in while your old roof is torn off and the new one isn't yet sealed. If water pours into your attic and ruins your insulation or electrical systems, General Liability insurance is what pays for those repairs. This coverage also protects your property from damage caused by heavy equipment, such as a shingle elevator cracking your driveway or falling debris smashing a neighbor's window. General Liability insurance for roofing is a specific policy that covers the cost of third-party property damage or bodily injury, ensuring that your home's structure and your neighbor's assets are protected up to the policy's stated limits.
Workers' Comp: Why Homeowners Are at Risk
The most significant financial threat to a homeowner isn't property damage; it's a personal injury lawsuit. If a roofing crew member is injured on your property and the contractor doesn't have active Workers' Compensation, that worker may have the legal right to sue you for medical expenses and lost wages. This is a common trap when hiring companies that use uninsured subcontractors to cut costs. You become the "de facto" employer in the eyes of the law, making your personal assets vulnerable.
The Michigan Workers' Disability Compensation Agency mandates that most employers carry this coverage to protect both the worker and the public. This insurance prevents your homeowner's policy from being targeted if an accident occurs on-site. By choosing a locally owned roofing partner that prioritizes full coverage, you ensure that every person on your roof is a professional who is fully accounted for. This transparency is the only way to guarantee that a project meant to improve your home doesn't end up costing you your savings.
How to Verify a Roofing Company's Credentials in Michigan
Trust is the foundation of any home improvement project, but in the construction industry, trust must be verified with hard evidence. Finding a legitimate insured roofing company Michigan residents can rely on requires more than a handshake and a verbal promise. A professional contractor expects you to ask for credentials. They'll have their documentation organized and ready to share because they understand that transparency protects both parties. If a contractor seems annoyed or evasive when you ask for proof of coverage, it's a clear signal to look elsewhere.
The 3-Step Verification Process
The first step in your due diligence is visiting the Michigan Department of Licensing and Regulatory Affairs (LARA) website. Use their verify license search tool to check the company's name. You are looking for an "Active" status for either a Residential Builder or a Maintenance & Alteration Contractor license. This confirms the contractor is legally allowed to perform roofing work in the state and has met the necessary educational requirements.
Once the license is confirmed, request a Certificate of Insurance (COI). You shouldn't just accept a printed copy handed to you during the estimate. Instead, ask the contractor to have their insurance agent email the COI directly to you. This simple step ensures the policy hasn't been canceled due to non-payment and hasn't been doctored. Finally, cross-reference the company name on the insurance document with the name on your contract and the LARA database. Every detail must match exactly to ensure the coverage actually applies to your specific project and property.
Red Flags to Watch For
Watch out for contractors who only offer a policy number. A number without a formal certificate is meaningless; it doesn't prove the policy is currently in force or that it covers high-risk roofing work specifically. Vague claims about "being covered" or "having everything taken care of" are equally dangerous. Real coverage is a significant business expense, which is why uninsured companies often provide significantly lower bids. If one estimate is thousands of dollars less than the others, they might be skipping out on high-risk insurance premiums. This "savings" disappears the moment an accident occurs and the liability falls on your shoulders.
Before any crew steps on your roof, ask these specific questions to gauge their professionalism:
- "Can I have your insurance agent's contact information to verify your current standing?"
- "Are your workers direct employees or independent subcontractors, and are they all covered by your workers' comp policy?"
- "Does your General Liability policy have a specific 'roofing' classification?"
At Miller's Home Improvement, we believe that transparency is the foundation of a successful project. With 13 years in business and 25 years of owner experience, we provide our credentials upfront. We want you to proceed with total peace of mind, knowing that your home is in the hands of a verified, professional team.
Insurance Claims and Storm Damage Restoration in Detroit
A storm damage restoration is more than a simple repair; it is a legal and financial negotiation between you and your insurance carrier. Choosing an insured roofing company Michigan homeowners trust ensures that your contractor can speak the language of the insurance adjuster. Professional adjusters prioritize estimates from contractors who maintain active credentials because it guarantees the work will be performed according to industry standards. This relationship is vital for ensuring your claim covers the full scope of necessary repairs, including mandatory updates required by the Michigan Residential Code. When a contractor is fully insured, the insurance company knows they are dealing with a professional entity that adheres to state safety and quality mandates, which often speeds up the approval process. It also ensures that if the adjuster misses a code-required item, like a full tear-off when a roof already has two layers, your contractor has the professional standing to advocate for the correct scope of work.
Navigating Wind and Hail Damage Claims
Identifying wind-blown shingles or hail bruises requires a trained eye. Before you file a claim, a professional assessment is necessary to determine if the damage meets your policy's threshold. An insured contractor doesn't just look for missing shingles; they evaluate the integrity of the entire roofing system, including the flashing and underlayment. In Michigan, any restoration must comply with the state's ice and water shield mandate for eaves and valleys. We specialize in documenting these specific requirements to ensure your carrier pays for a code-compliant installation. You can learn more about Spotting Hidden Hail Damage Before Your Deadline to protect your claim rights and ensure your home remains protected.
The Dangers of Storm Chasers
After a major weather event, "storm chasers" often flood the Detroit area. These transient companies follow storms across state lines, and while they may show you an insurance certificate, it is often invalid for work performed in Michigan. Insurance policies are frequently state-specific. A policy that covers a crew in Ohio or Indiana may not provide the necessary Workers' Compensation protection required by Michigan law. If a problem arises six months later, these companies are often impossible to find, leaving you with a voided warranty. Hiring a local insured roofing company Michigan residents have relied on for over a decade prevents these transient risks. Eric Miller has spent 25 years building a reputation in Southeast Michigan, ensuring our neighbors receive the stability of a local, owner-operated partner. If you suspect your roof has been compromised, contact Miller's Home Improvement for a professional inspection.
Peace of Mind with Miller's Home Improvement
Choosing an insured roofing company Michigan residents can rely on is about more than just checking a box; it's about partnering with a team that respects your investment. At Miller's Home Improvement, we don't just carry insurance because it's required. We carry it because we value the stability and longevity of our community. As a fully insured roofing company Michigan homeowners trust, we take pride in doing things correctly the first time. Eric Miller brings over 25 years of owner experience to every job site, ensuring that the high standards we discuss in our paperwork are reflected in our physical craftsmanship. As an owner-operated business, our accountability is direct. You aren't dealing with a revolving door of sales reps; you're dealing with a local professional whose reputation is built on 13 years of successful projects in the Detroit area.
Residential and Commercial Expertise
Our deep roots in Southeast Michigan allow us to provide tailored solutions for a diverse range of properties. Whether we're working on a residential roof in Detroit or a complex commercial project in Macomb County, our approach remains meticulous. We specialize in high-performance flat roofing systems, including PVC, EPDM, and Torch Down Flat Roofing, providing business owners with durable, weather-resistant barriers that stand up to harsh Michigan winters. Every project begins with a complete roof tear-off when necessary, a process we manage with extreme care to protect your landscaping and property. We don't believe in shortcuts like shingle-overs if they compromise the structural integrity of your home. By removing every layer of old material, we can inspect the underlying deck for rot or damage, ensuring your new roof has a solid foundation.
Start Your Project with Confidence
Hiring a seasoned master craftsman means you're getting a proactive guide who anticipates problems before they occur. Eric Miller provides direct project oversight, meaning your roof replacement isn't left to chance or an unverified crew. We maintain full transparency regarding our licensing and insurance status, and we're always happy to provide current documentation directly from our agents. This commitment to honesty is why our neighbors continue to trust us with their most valuable assets. You deserve a roofing partner who prioritizes your safety and financial security from the initial inspection to the final cleanup. We handle the technical details and the paperwork so you can focus on your daily life. If you're ready to experience the difference that professional accountability makes, Get Your Free Roofing Estimate Today and take the first step toward a secure, long-lasting roof.
Secure Your Investment with Professional Accountability
Protecting your home starts with choosing a partner who values your financial security as much as the integrity of your roof. We've explored how active General Liability and Workers' Compensation policies serve as your only real defense against property damage and personal liability. By verifying credentials through the Michigan LARA portal and insisting on a direct Certificate of Insurance, you eliminate the risks associated with transient labor or storm chasers. A professional insured roofing company Michigan homeowners can trust provides the transparency needed for successful storm damage claims and long-term property value.
Miller's Home Improvement brings a steady, disciplined approach to every project. As an owner-operated business led by Eric Miller, we offer the quiet confidence that comes from 25+ years of owner experience. We are fully licensed and insured in Michigan, ensuring that every shingle laid and every tear-off performed is backed by our personal commitment to quality. Don't leave your most valuable asset to chance. Schedule Your Free In-Home Roofing Estimate with Miller's Home Improvement today. We look forward to providing the durable, meticulous protection your family deserves.
Frequently Asked Questions
Is it illegal to hire an uninsured roofing company in Michigan?
While it isn't technically a crime for a homeowner to hire them, it's a violation of state licensing regulations for a contractor to operate without required insurance. Michigan law requires licensed contractors to carry general liability to protect the public. Hiring an uninsured company puts you at extreme financial risk. It's always better to partner with an insured roofing company Michigan homeowners trust to ensure every aspect of your project complies with state safety mandates.
What happens if a roofer gets hurt on my property and they don't have insurance?
You may be held personally liable for their medical expenses and lost wages if the contractor lacks Workers' Compensation. Without this coverage, an injured worker can sue the homeowner directly for damages. Your personal assets, including your savings and home equity, could be at risk. This is why insurance isn't just for the contractor; it's a vital legal shield for your family and your future financial stability during construction.
Does my homeowner's insurance cover roof damage if the contractor is uninsured?
Most homeowner's policies will deny claims for damage caused by an uninsured contractor's negligence. Carriers often require that you hire licensed and insured professionals for major structural work. If an uninsured roofer causes a fire or a major leak during a Detroit rainstorm, you might have to pay for those repairs out of your own pocket. Professional coverage ensures your carrier remains responsible for legitimate property damage claims that occur during the project.
How do I check if a Michigan roofer's license is active?
You can verify any contractor's status through the Michigan Department of Licensing and Regulatory Affairs (LARA) website. Search by the business name or license number to confirm they hold an active Residential Builder or Maintenance & Alteration Contractor license. This step is essential because a license must be renewed every three years to remain valid. At Miller's Home Improvement, we encourage every client to verify our 13 years of business standing before any work begins.
Why do insured roofing companies charge more than others?
Higher premiums for General Liability and Workers' Compensation are significant business expenses that legitimate contractors must cover to operate legally. These costs reflect a commitment to safety and professional accountability. While an uninsured crew might offer a lower bid, they're often cutting corners on your protection to save on their overhead. Investing in an insured roofing company Michigan ensures you aren't left with a massive legal bill if an accident occurs on your roof.
Can a roofing company be licensed but not insured?
Yes, it's possible for a contractor to hold a state license but let their insurance policies lapse. A license proves they passed an exam and met educational requirements, but it doesn't guarantee they've paid their recent insurance premiums. This is why you must ask for an updated Certificate of Insurance (COI) in addition to their license number. We always provide current proof of coverage to show our commitment to maintaining the highest professional standards.
What should I do if a contractor refuses to show proof of insurance?
You should immediately stop the estimation process and look for another contractor. A refusal to provide a Certificate of Insurance is a major red flag that suggests they're either uninsured or trying to hide a lapsed policy. Professional roofers in Southeast Michigan have these documents ready because they understand your need for peace of mind. Never allow a crew to step on your property without seeing verifiable proof of active coverage from their insurance agent.
Are there specific insurance requirements for commercial flat roofing in Michigan?
Commercial projects often require significantly higher liability limits than residential work due to the increased risk and property value. While there's no separate commercial license in Michigan, contractors must be registered locally and carry robust policies for systems like PVC, EPDM, and Torch Down flat roofing. These high-limit policies protect the business owner from the catastrophic costs of structural failure or fire during the specialized installation process required for industrial flat roofs.


